Preparing for retirement can feel overwhelming when you have several financial priorities competing for your attention. You may be paying a mortgage, supporting your family, managing investments, or saving for other major goals while trying to determine whether you will have enough money to retire comfortably.
The challenge is not simply saving more. It is making sure your savings, investments, expenses, and future income work together. Without a coordinated strategy, you could overlook important costs, take unnecessary investment risks, or discover too late that your retirement savings may not meet your expectations.
A practical retirement plan helps you understand where you stand today and which decisions could improve your long-term financial position. With regular reviews and realistic goals, you can make steady progress toward a retirement lifestyle that fits your needs.
Establish Your Financial Priorities Before You Retire
The first step is understanding how retirement fits into your broader financial life. Your retirement goals should reflect your current resources, family responsibilities, expected expenses, and preferred retirement age.
Start by reviewing your income, monthly spending, debts, savings, investments, and insurance coverage. This information provides a foundation for identifying financial strengths and areas that may need improvement.
Next, separate your goals into short-term and long-term priorities. Building an emergency fund, reducing high-interest debt, and saving for retirement may all be important, but the appropriate balance depends on your circumstances.
For example, someone with unstable income may need additional cash reserves before increasing investment contributions. Someone with manageable expenses and an established emergency fund may have more flexibility to increase retirement savings.
Setting clear priorities makes financial decisions easier because you can evaluate each choice against your overall objectives.
Calculate How Much Income You May Need
A common retirement-planning mistake is focusing on the total amount saved without considering how much income that money may provide.
Your retirement budget should account for essential expenses such as housing, food, utilities, transportation, insurance, and healthcare. You should also consider discretionary spending, including hobbies, travel, entertainment, and family activities.
Remember that your expenses may change after you leave the workforce. You might spend less on commuting but more on healthcare, home maintenance, or leisure activities.
Once you estimate your future expenses, compare them with potential income from retirement accounts, Social Security, pensions, investments, and other resources.
This comparison can help reveal whether you are on track or need to adjust your savings rate, spending expectations, or retirement timeline.
Make Your Retirement Savings More Consistent
Building retirement savings often becomes easier when contributions are part of your regular financial routine.
If you participate in a workplace retirement plan, review your contribution percentage and understand any employer matching benefits. Matching contributions can increase your savings when available, subject to your plan's rules.
You may also consider increasing contributions gradually when your income rises or a major expense disappears. This approach can help you save more without requiring a sudden change to your lifestyle.
However, avoid making retirement contributions the only focus of your financial strategy. Maintaining accessible emergency savings and managing expensive debt can help protect your overall financial stability.
Your goal should be to develop a savings routine that is sustainable today and supports your future income needs.
Evaluate Investments Based on Your Retirement Timeline
Your investment strategy should reflect when you expect to need the money and how much risk you can reasonably accept.
Investments with greater growth potential may also experience larger fluctuations. If you are many years away from retirement, you may have more time to recover from certain market declines. If retirement is approaching, a significant loss could have a greater effect on your plans.
Consider diversification, investment expenses, liquidity, and the role of each account in your overall portfolio.
Avoid changing your investment strategy simply because markets are rising or falling. Instead, review whether your portfolio remains appropriate for your goals, financial resources, and time horizon.
Regular investment reviews can also help identify excessive concentration or fees that may reduce long-term results.
Prepare for Inflation and Rising Living Costs
Inflation can gradually reduce the purchasing power of your savings. Money that comfortably covers your expenses today may not provide the same lifestyle several years into retirement.
When estimating future costs, consider the possibility that housing, healthcare, food, utilities, and other essentials will become more expensive.
Your plan should also account for the possibility that retirement could last for decades. A strategy that works during the first few years may need adjustments later as expenses and income change.
Diversified investments may help address long-term growth needs, but returns are never guaranteed. Reviewing your spending assumptions and financial resources regularly can help you recognize when adjustments may be necessary.
Understand the Role of Taxes in Retirement
The money you save and the money you can ultimately spend are not always the same. Taxes may affect retirement account withdrawals, investment income, and other sources of retirement income.
Traditional retirement accounts, Roth accounts, and taxable investments can have different tax characteristics. Understanding those differences may help you evaluate how and when to use your assets.
Tax considerations should be part of your retirement strategy rather than an issue addressed only after you stop working.
Professional financial planning services can help you review how savings, investments, expenses, and potential retirement income fit together. For complicated tax decisions, consult a qualified tax professional who can evaluate your specific circumstances and applicable rules.
Protect Your Retirement Plan From Unexpected Expenses
Unexpected costs can disrupt even a carefully prepared financial plan. A major home repair, vehicle replacement, medical bill, or family emergency may require money that was intended for other purposes.
An emergency reserve can provide a source of accessible funds for these situations. The appropriate amount depends on your regular expenses, income sources, insurance coverage, and financial responsibilities.
Review your insurance coverage as well. Health, home, auto, and other relevant policies may help manage certain financial risks, although coverage limits, exclusions, and deductibles matter.
Planning for unexpected expenses does not eliminate uncertainty. It gives you more options when circumstances change.
Create a Sustainable Retirement Income Strategy
When retirement begins, your financial priorities shift from primarily accumulating assets to using those assets to support your lifestyle.
Your income strategy may combine retirement account withdrawals, Social Security, pension payments, investment income, and other resources. Each source may have different timing, tax implications, and levels of predictability.
Consider how much you expect to spend, which income sources can cover essential expenses, and how your investments might support longer-term needs.
It is also important to consider how withdrawals may affect your portfolio during a market downturn. Taking money from investments after significant losses can place additional pressure on a retirement portfolio.
A carefully reviewed withdrawal strategy can help you understand these risks and evaluate adjustments when necessary.
How Professional Retirement Planning Services Can Help
Retirement decisions often involve several connected financial issues. An investment choice can affect your future income, a withdrawal can influence your taxes, and a spending decision can change how long your savings may last.
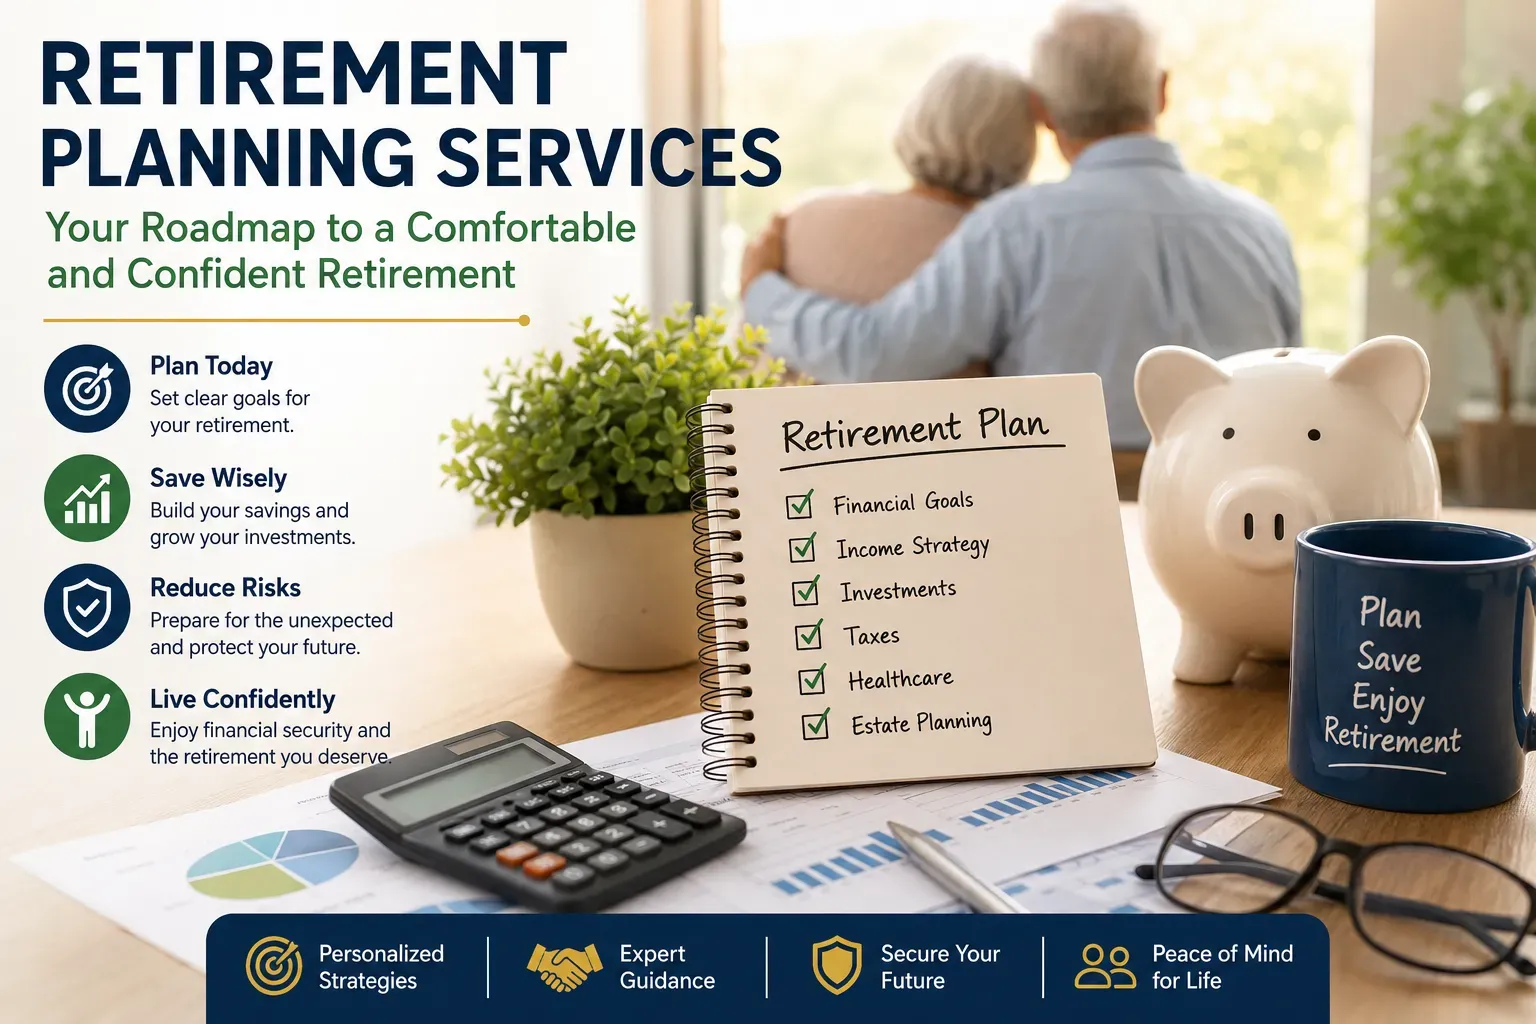
Professional Retirement Planning services can help organize these considerations into a coordinated strategy. Depending on the services offered, this may involve reviewing retirement readiness, estimating future expenses, evaluating investments, and identifying potential gaps between expected income and spending.
For individuals seeking retirement financial planning in Ellisville, personalized guidance can help connect financial decisions to specific retirement goals and establish a process for reviewing progress over time.
Before working with an adviser, ask about qualifications, fees, compensation, services, and how recommendations will be tailored to your circumstances.
Review Your Financial Plan as Your Life Evolves
A retirement strategy should not remain unchanged for years. Your income, family responsibilities, investment values, and retirement goals may shift over time.
Review your plan at least periodically and after major events such as a job change, home purchase, inheritance, significant debt payoff, or change in your intended retirement date.
Take the Next Step Toward Retirement Readiness
A stronger retirement strategy begins with a clear understanding of your financial position and the lifestyle you want to support. From there, you can estimate future expenses, review savings, evaluate investments, prepare for taxes, and consider how your assets may generate income.
You do not need to make every decision at once. Start with the areas that need the most attention, establish realistic goals, and review your progress regularly.
Consistent saving and informed adjustments can help you address financial challenges before they become urgent. With a flexible plan that reflects your needs and changing circumstances, you can build a more organized foundation for the retirement years ahead.


Share this page with your family and friends.